At a Glance
- What it is: a marketplace that matches you with HELOC lenders, not a lender itself
- Average HELOC rate: 7.28% in LendingTree’s April 2026 data, the latest period on its page as of October 9, 2026, with offers as low as 5.95%
- Borrowing limit: usually about 85% of your home’s value, minus your mortgage
- Typical closing: 2 to 6 weeks, with the fastest lenders at about 5 to 7 days
- Investment property: possible, but stricter, with a 720 minimum credit score
- Cost to compare: free, and LendingTree says it is paid by lenders
A HELOC is secured by your home, so the headline rate is only part of the story. This review covers four things: rates, the calculator, investment property HELOCs and fast closings.
Identify: What LendingTree Offers, and What It Does Not
LendingTree is a loan marketplace. You fill out one form, and it says it matches you with up to five lenders from a network of more than 300, who then compete for your business. It cites more than 25 years in business, which is a company figure.
It does not lend money itself, and this page has no promo code. The “deal” is free comparison, plus free credit monitoring and a free credit score through its Spring product. Rates and terms come from each lender and are not guaranteed.
Rate snapshot as of October 9, 2026. The table below shows average HELOC rates from offers made to LendingTree customers in April 2026, the most recent month on its page. For a newer reference point, Bankrate’s survey put the national average HELOC rate at 7.33% on October 7, 2026, based on a 30,000 dollar line, a 700 FICO score, and an 80% combined loan-to-value ratio. Your own rate will depend on your score, line size, and lender, and LendingTree refreshes its table often.
| Credit Score | Average APR |
|---|---|
| 800 and above | 6.77% |
| 740 to 799 | 7.07% |
| 670 to 739 | 7.65% |
| 580 to 669 | 8.55% |
By loan size, the average runs from 7.74% on 25,000 to 49,999 dollars down to 7.06% for 100,000 to 149,999 dollars (April 2026). LendingTree says a rate at or below the 7.28% average is a good sign. Most HELOC rates are variable, so payments can change.
Best For: Homeowners who want several offers without applying lender by lender.
Evaluate: What Your Line Could Be Worth, Using the LendingTree HELOC Calculator
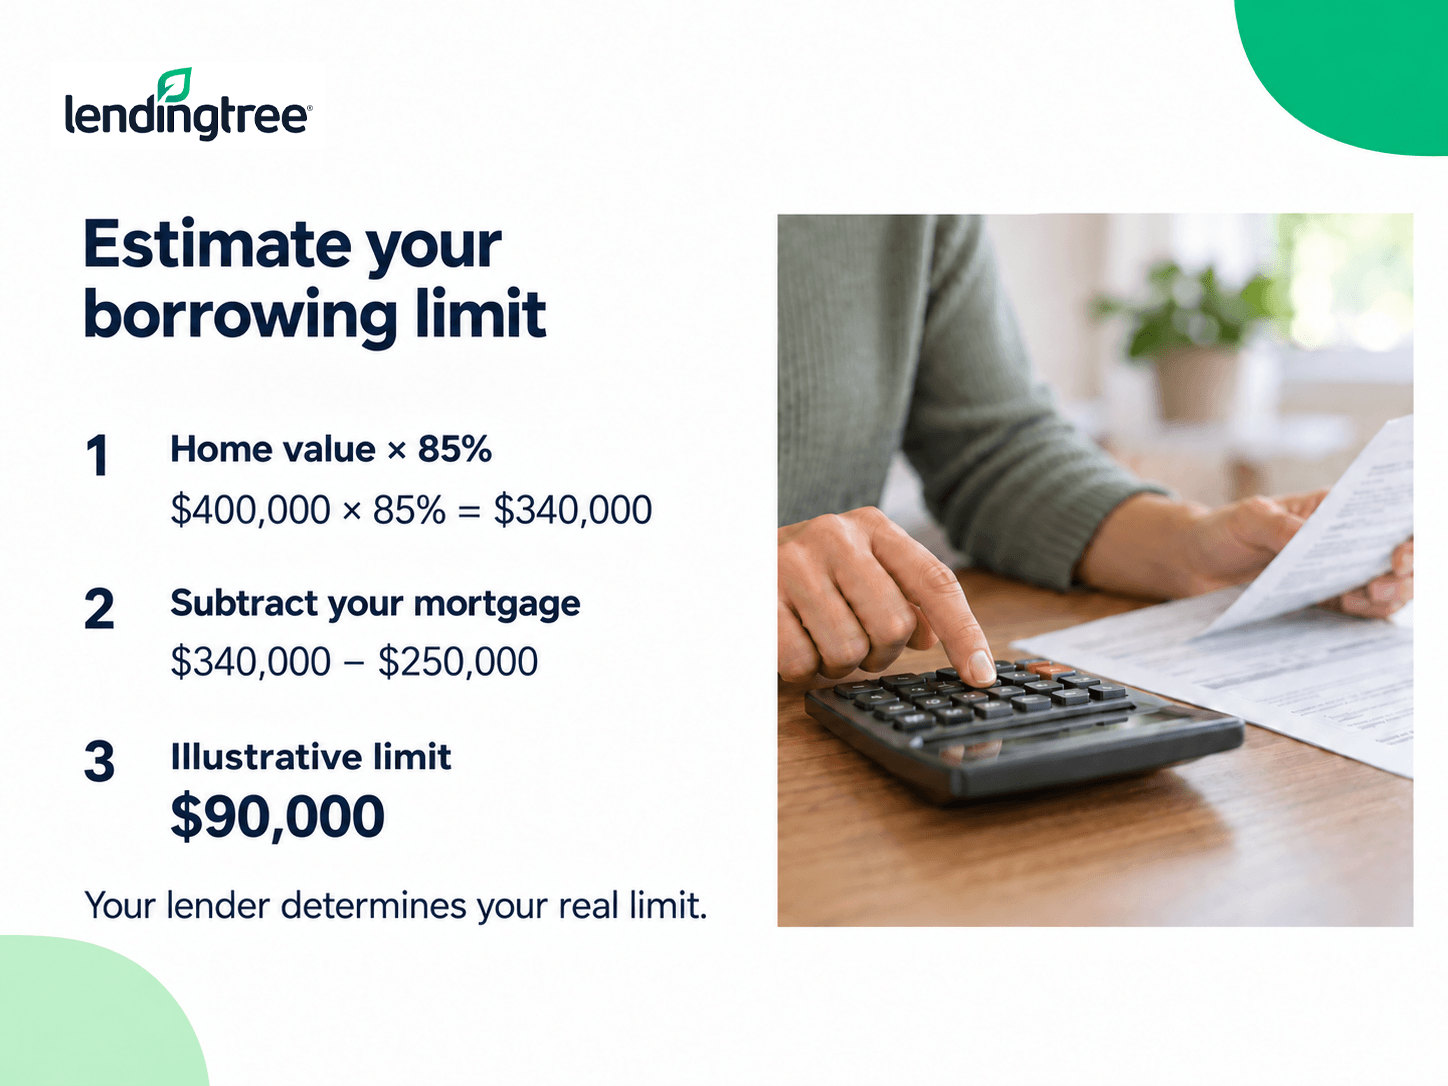
Most lenders let you borrow only a share of your equity. The calculator uses this formula: borrowing limit equals your home value times 85%, minus your mortgage balance.
Our own illustration: a 400,000 dollar home with a 250,000 dollar mortgage gives 340,000 minus 250,000, or about 90,000 dollars. Your real limit depends on the lender.
LendingTree lists common minimums that most lenders share: a 620 credit score, a debt to income ratio of 43% or less, and a loan to value ratio of 85% or less.
The calculator page also shows what a full draw could cost. These figures are LendingTree’s own estimates. Each example below assumes you draw the full amount and repay it over about 20 years.
| HELOC Amount | Interest Only Payment | Principal and Interest Payment |
|---|---|---|
| 50,000 dollars | About 337 dollars | About 421 dollars |
| 75,000 dollars | About 471 dollars | About 606 dollars |
| 100,000 dollars | About 575 dollars | About 769 dollars |
How to read the table: the payments fit a fixed APR of about 8.1% on the 50,000 dollar line, 7.5% on the 75,000 dollar line, and 6.9% on the 100,000 dollar line. Interest only payments cover the draw period, while the principal and interest payments spread the full balance over about 20 years. A variable rate, a different APR, or a smaller draw will change your numbers, so use these as a guide and run the calculator with your own offer.
Closing costs run about 2% to 5% of the credit line. On a 100,000 dollar line, LendingTree lists 2,000 to 5,000 dollars, putting its total borrowing cost at roughly 187,000 to 190,000 dollars. That total assumes a full 100,000 dollar draw repaid over about 20 years at a fixed 6.9% APR, which is about 184,600 dollars in payments, plus the 2,000 to 5,000 dollars in closing costs. It does not include an interest only period or any later rate change. Interest only payments look cheap at first, but they can rise when the draw period ends.
Best For: Borrowers who want a realistic limit and payment before they apply.
Compare: Investment Property HELOCs vs. Primary Home HELOCs
A HELOC on a rental uses that property, not your home, as collateral. LendingTree says these are harder to find and cost more. Its comparison:
| Requirement | Investment Property HELOC | Primary Home HELOC |
|---|---|---|
| Maximum debt to income | 40% to 50% | 43% to 50% |
| Maximum loan to value | 80% | 80% to 85% |
| Minimum credit score | 720 | 620 to 680 |
| Cash reserves | Often 6 to 18 months | Usually not required |
| Occupancy | Tenant in place with rental history | You live there |
Lenders usually count only 75% to 80% of projected rent when they qualify you. On tax, LendingTree says interest is deductible only if you use the money to buy, build or substantially improve the property. Ask a tax professional before you rely on that.
It names TD Bank, with offers in 15 states, and Fifth Third Bank, with digital service in 45 states, as lenders that offer these lines.
Best For: Landlords with a tenant, strong credit and cash reserves.
How LendingTree Compares With Going Direct
| Category | LendingTree | Figure | Rate | Bank of America |
|---|---|---|---|---|
| Model | Marketplace matching you with lenders | Direct online lender | Direct online lender | Direct bank |
| Speed claim | 5 to 7 days with the fastest lenders | 5 days to close | 5 days to close | Check site |
| Maximum loan | Set by lender | 400,000 dollars | 400,000 dollars | Check site |
| Rate type | Mostly variable | Fixed on the first draw | Check site | Variable, with a fixed option |
| Notable perk | Many offers, one form | Fast digital closing | Digital closing | No closing costs, application or annual fees, per LendingTree |
These details come from LendingTree’s own pages and may be out of date. Check each lender before you decide.
Browse Investment Property HELOCs
Recommend: How to Get the Fastest HELOC Closing Without Overpaying
LendingTree says a HELOC typically takes two to six weeks to close, while the fastest lenders can close in about five to seven days. A home equity loan takes two to eight weeks, and a cash-out refinance about six weeks. Its fastest list includes Rate and Figure at about five days, Better Mortgage at seven, and PenFed at 15.
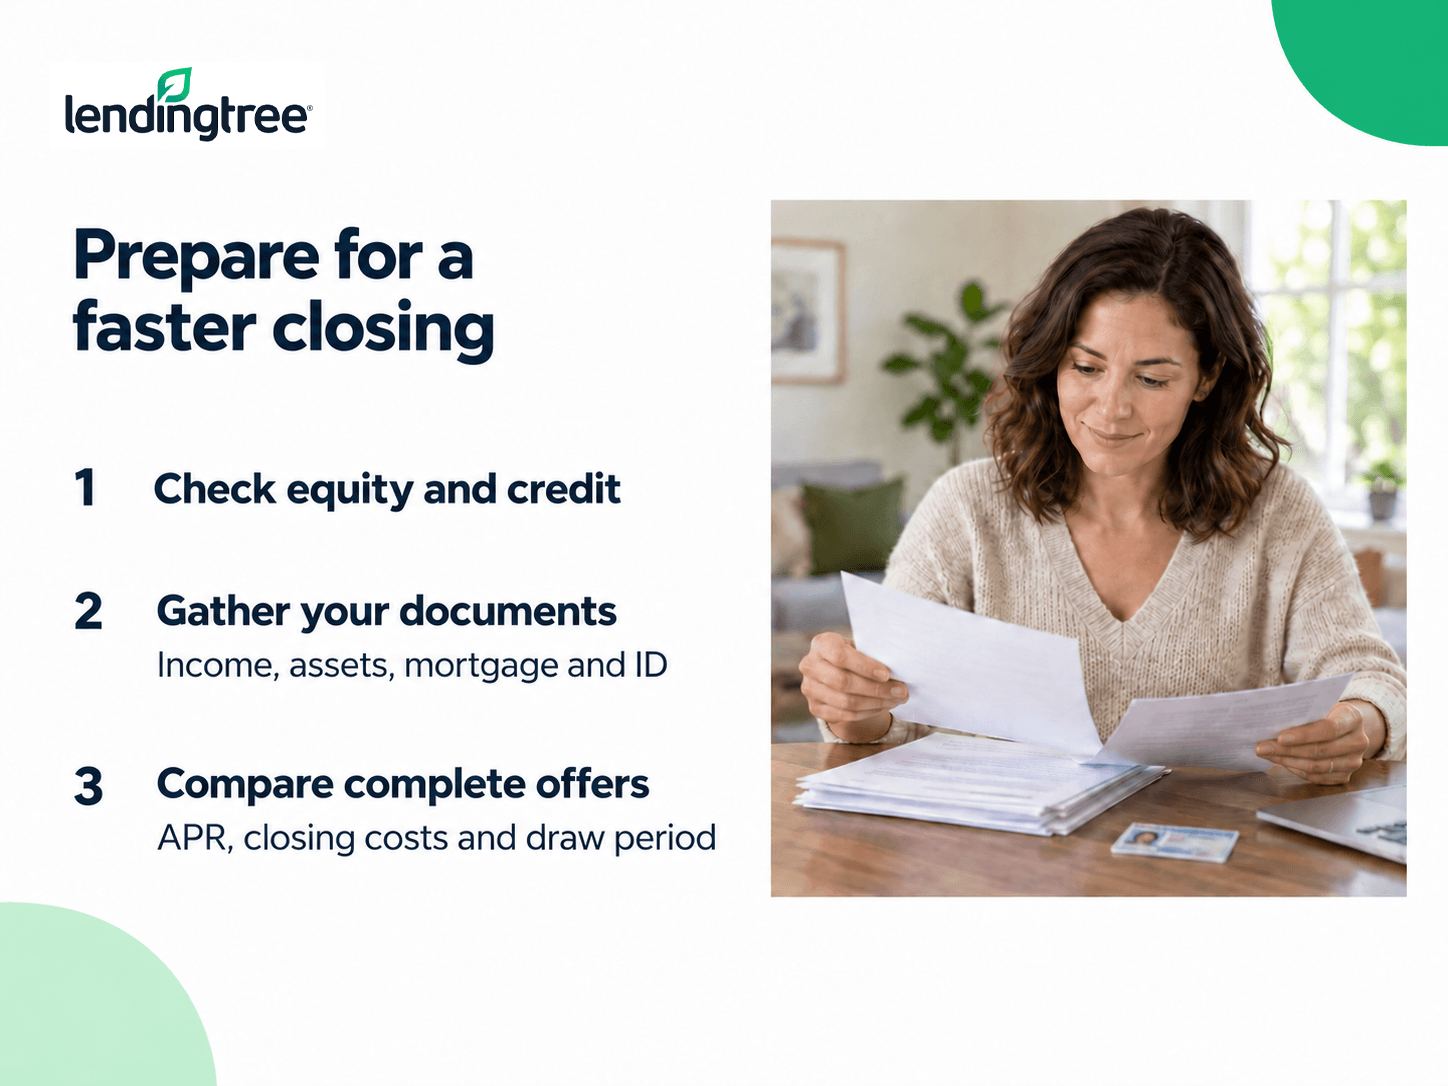
Speed comes from automation. LendingTree’s three tips: know your limit, pick a lender that uses an automated home valuation instead of an in person appraisal, and have your income, asset and employment papers ready. On a primary home, a three day right of rescission also applies.
A practical order of steps:
- Run the calculator and check your equity.
- Pull your credit report and fix any errors.
- Gather pay stubs, tax returns, mortgage statements and ID.
- Prequalify through LendingTree and compare at least three offers.
- Compare APR, closing costs and draw period, not just speed.
LendingTree says several applications within a 14 to 45 day window usually count as one credit inquiry.
Best For: Borrowers with a time sensitive need and their documents ready.
Why Homeowners Like a HELOC
- Lower cost. HELOC rates are generally lower than credit card and personal loan rates.
- Pay for what you use. You repay only what you draw, plus interest.
- Reusable. Repay and borrow again during the draw period.
- Gentle start. Interest only payments are often available at first.
- Falling rates. On LendingTree’s latest published data, the average offer on a 100,000 dollar line was 7.09% in April 2026, against 8.46% in April 2025.
Who Is It For?
- Homeowners with at least 15% equity who want to compare several lender offers.
- Borrowers who need ongoing access to funds for renovations or medical bills.
- Landlords with strong credit and reserves who want to tap rental equity.
- People who can handle a variable rate and a payment that may rise.
- Shoppers who value speed and have every document ready to upload.
Frequently Asked Questions
Is LendingTree a lender?
No. It matches you with lenders in its network, and lenders pay LendingTree.
What credit score do I need?
Most lenders ask for at least 620. Investment property lines usually need 720.
How fast can a HELOC close?
Typically two to six weeks. The fastest lenders advertise five to seven days.
Is there a promo code?
We found none on the page. The value is free comparison.
Can I use a HELOC on a rental property?
Yes, with stricter rules, higher rates and fewer lenders.
Final Verdict
LendingTree makes it easy to see several HELOC offers at once, and its calculator gives you a realistic limit before you apply. Compare APR and closing costs, not just speed, and borrow only what you can repay if your payment rises. For rentals, expect tougher rules.